Roof and exterior
Roofing materials, flashing, gutters, vents, windows, doors, siding, stucco, fencing, and debris impact.
Wind and storm claim representation
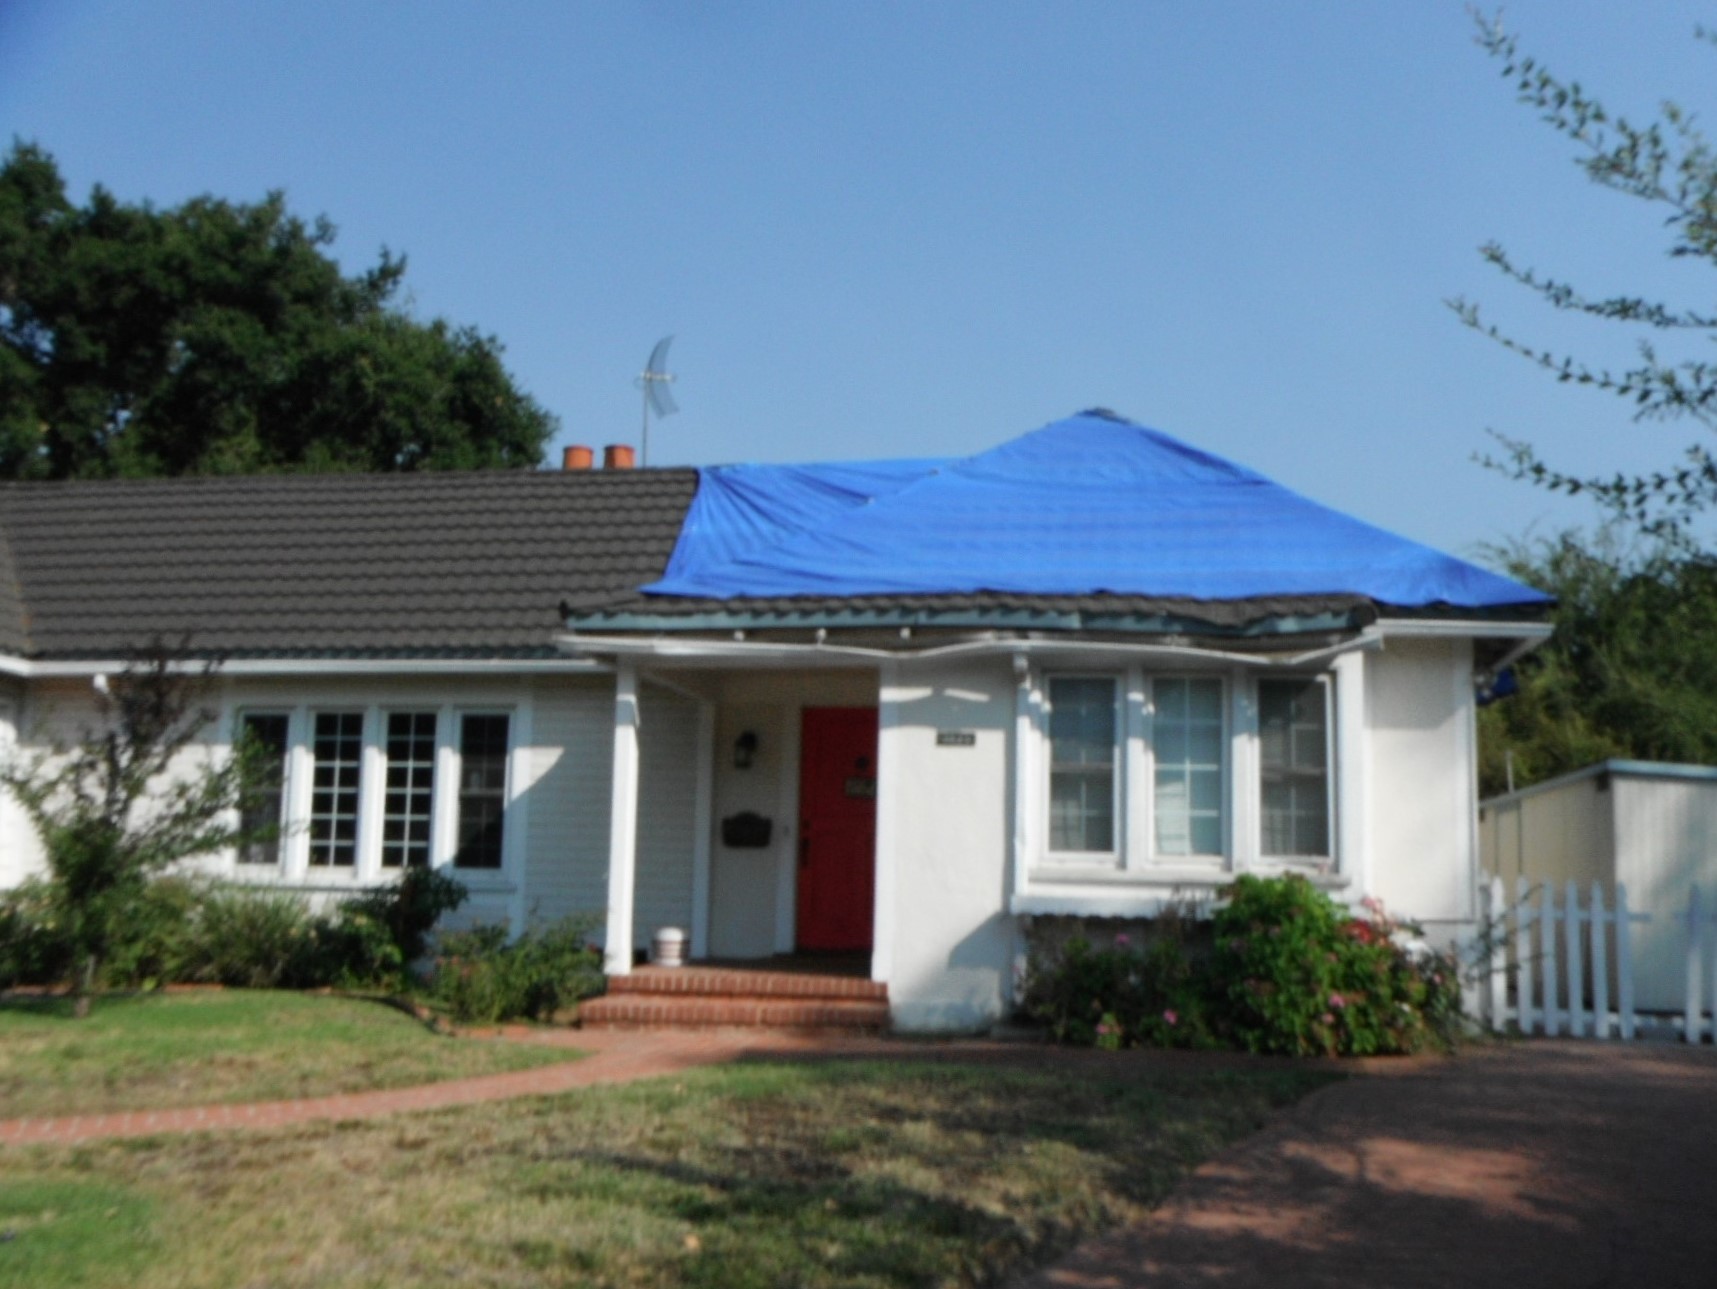
Wind can affect roofing, exterior systems, windows, interiors, contents, and the building envelope. Adjust First helps policyholders identify, document, and negotiate the complete storm-related loss.
 ✓Roof, exterior, and interior claim support
Beyond the first inspection
Missing or lifted roofing materials may be the most visible condition, but wind and rain can also affect underlayment, flashing, vents, exterior finishes, attics, ceilings, walls, insulation, flooring, and contents.
We review the policy and carrier estimate, document the full repair scope, coordinate appropriate experts, and present the claim on behalf of the policyholder.
Roofing materials, flashing, gutters, vents, windows, doors, siding, stucco, fencing, and debris impact.
Water intrusion, ceiling and wall finishes, insulation, flooring, electrical components, and personal property.
Access, matching, building code considerations, temporary protection, and a complete restoration scope.
Our storm-claim process
We develop the claim around the actual property conditions and applicable policy—not a one-size-fits-all checklist.
We organize the date of loss, weather event, reported conditions, emergency response, photographs, and available supporting information.
Shingles, tile, underlayment, flashing, vents, gutters, windows, stucco, siding, and other exterior components may require evaluation.
Wind-created openings can allow rain into attics, ceilings, walls, insulation, flooring, and personal property.
We document damaged materials, access requirements, matching considerations, code-related items, and the work needed to restore the property.
Reasonable emergency protection, mitigation, and applicable temporary living or business expenses are organized for the claim.
Adjust First prepares the claim presentation, coordinates inspections, responds to scope disputes, and negotiates with the carrier.
Selected wind-damage results
Prior results do not guarantee a similar outcome. Every claim depends on its facts, damage, documentation, and policy terms.
The Adjust First standard
Our goal is not to create conflict. Our goal is to create clarity—and a claim record that can withstand serious review.
Every material position should be traceable to the policy, the facts, the damage, and the cost.Coverage, endorsements, exclusions, conditions, and deadlines reviewed together.
Visible and less obvious consequences investigated, measured, and connected.
Repair methods, quantities, code requirements, sequencing, and trade coordination.
Qualified construction and technical experts coordinated when the claim requires them.
Submissions, responses, requests, and unresolved issues organized in writing.
Start with a conversation
Tell us what happened. Our team will review the situation and explain your next steps.